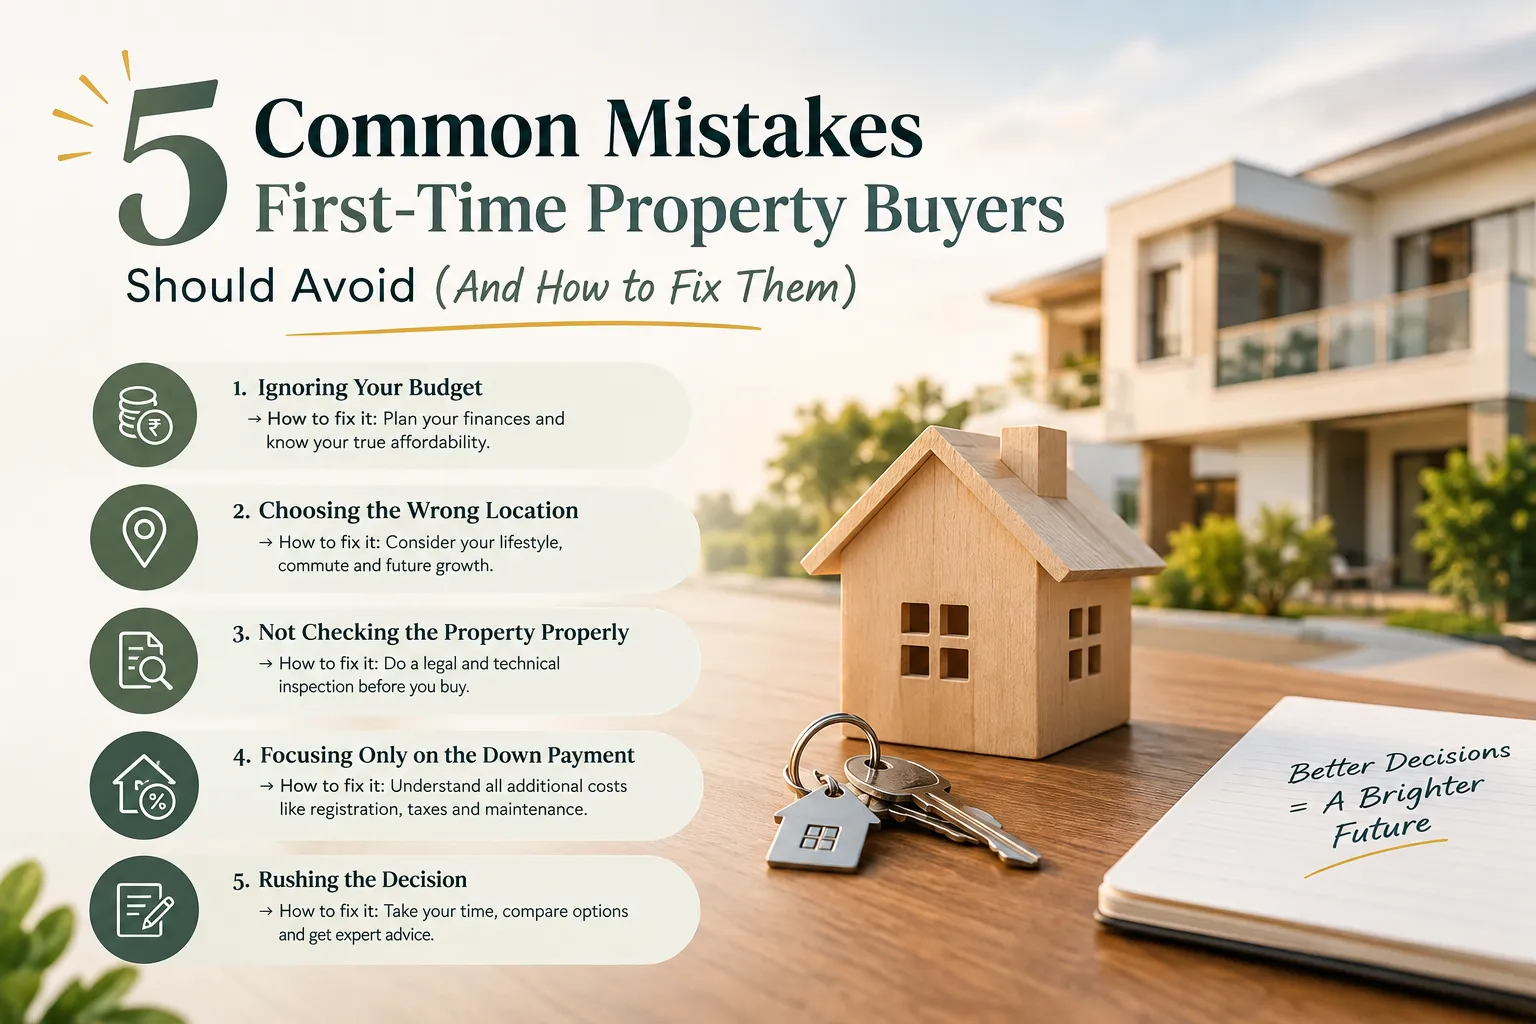
Buying your first property is exciting, but it can also be overwhelming. Many first-time buyers make avoidable mistakes that can lead to unexpected costs, financial pressure and long-term problems. In this guide, we explain 5 common first-time property buyer mistakes and how you can avoid them.
To help you navigate the process with confidence, here are the five most common mistakes first-time property buyers make—and how you can avoid them.
1. First-Time Property Buyer Mistakes: Focusing Only on the Purchase Price
It’s easy to look at a property’s listing price, run a quick calculation on a mortgage calculator, and assume you can afford it. However, the purchase price is only part of the equation.
The Pitfall
First-time buyers often forget to budget for initial closing costs and ongoing ownership expenses, leading to severe “sticker shock” after closing.
What to Look Out For:
- Closing Costs: Lender fees, title insurance, legal/attorney fees, and escrow deposits usually add 2% to 5% of the home’s total purchase price.
- Property Taxes & Insurance: These vary significantly by location and can increase annually.
- Maintenance & HOA Fees: Homeowners Association (HOA) or condo fees can add hundreds to your monthly bill. As a rule of thumb, set aside 1% to 2% of the home’s value annually for ongoing maintenance and repairs.
Pro Tip: Before placing an offer, request a full estimate of all closing costs from your lender and ask the seller/agent for an average of monthly utility expenses. In India, that estimate should cover stamp duty and registration, GST if the property is under construction, and the 1% TDS a buyer must deduct under Section 194-IA on a consideration of ₹50 lakh or more – the rules are set out by the Income Tax Department.
2. First-Time Property Buyer Mistakes: Skipping Mortgage Pre-Approval
Browsing real estate listings online is fun; getting your finances audited is not. Naturally, many buyers start touring homes long before they talk to a lender.
The Pitfall
House hunting without a formal pre-approval letter can lead to two major problems:
- Falling in love with properties that are outside your true budget.
- Losing out on your dream home because sellers won’t consider offers without a pre-approval letter in competitive markets.
Pre-Qualification vs. Pre-Approval
- Pre-Qualification: A quick, unverified estimate based on self-reported financial data.
- Pre-Approval: A formal evaluation where a lender verifies your credit score, income, debt, and tax returns to guarantee a specific loan amount.
Pro Tip: Get pre-approved by at least two or three different lenders to compare interest rates, loan terms, and origination fees before you start visiting open houses.
3. Buying for Today’s Lifestyle Instead of Future Needs
When you find a cozy downtown apartment or a trendy loft, it’s easy to focus solely on your current daily routine. However, a home is a long-term investment.
The Pitfall
Purchasing a property that fits your life today but fails to account for where you will be in 5 to 7 years. Selling and moving too soon can erase any equity you’ve built up due to transaction costs.
Questions to Ask Yourself:
- Are you planning to start or expand a family?
- Is there potential for job relocation or a shift to remote work requiring a dedicated home office?
- How are the local school districts and neighborhood safety ratings, even if you don’t have children right now (as this impacts resale value)?
- What will your commute look like if your workplace changes?
Pro Tip: Aim to buy a property that meets your foreseeable needs for at least 5 years to ensure you build enough equity to cover future selling and moving costs.
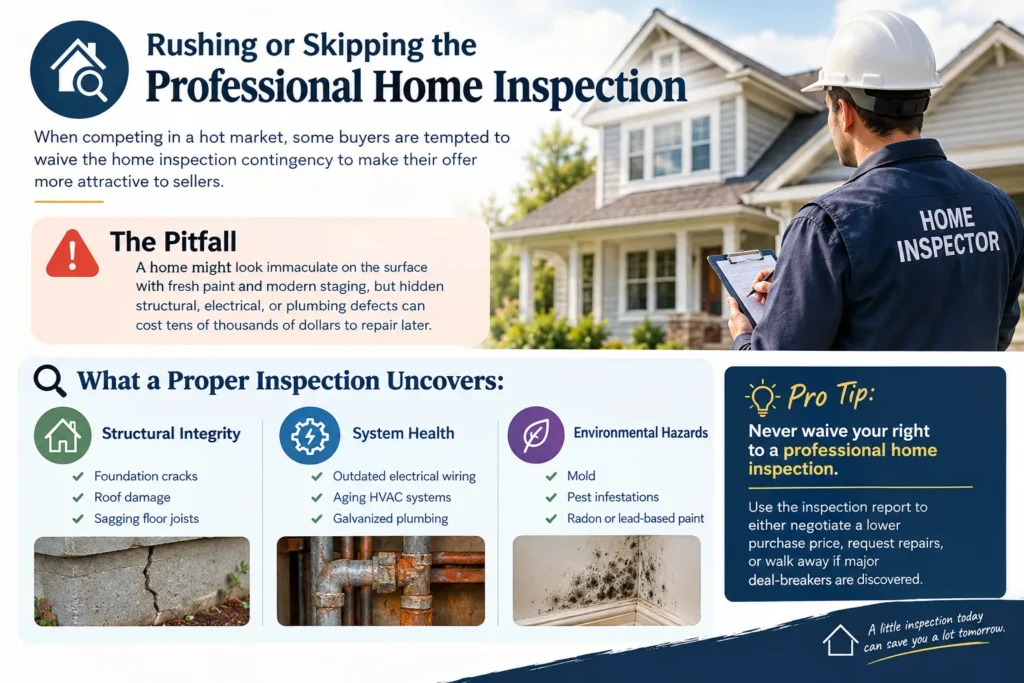
4. Rushing or Skipping the Professional Home Inspection
5. Letting Emotions Drive Price Negotiations
It’s easy to fall in love with a home’s charming curb appeal, custom kitchen, or backyard patio. But when emotions take over, rational financial judgment often flies out the window.
The Pitfall
Getting caught up in “bidding wars,” overbidding beyond market value, or stretching your budget to dangerous limits just to “win” the house.
How to Stay Objective:
- Rely on Comparable Sales (Comps): Look at recent sale prices of similar homes in the immediate area to determine fair market value rather than relying on emotional appeal.
- Set a Hard Upper Limit: Determine your maximum budget before entering negotiations and commit to walking away if the price exceeds it.
- Separate “Must-Haves” from “Nice-to-Haves”: Keep a clear checklist of non-negotiables (e.g., location, bed/bath count) versus aesthetic elements (e.g., paint colors, kitchen counters) that can easily be updated later.
Pro Tip: Treat the purchase like a business transaction. There will always be another property if a deal falls through.
Final Thoughts
Buying your first property doesn’t have to be overwhelming. By understanding these five common mistakes—budgeting for hidden fees, securing pre-approval early, planning for the future, insisting on a home inspection, and remaining objective during negotiations—you’ll set yourself up for a smooth and financially sound purchase.

Leave a Reply